Evyelland Construction

Credit Architecture • Lending Governance • NSW

Finance & Structuring Hub

Institutional borrowing power modeling, 100% offset debt preservation, auction valuation shortfall protection, and strategic equity leverage for Australian property buyers.

+3.00% APRA Minimum Stress Buffer
100% Offset Tax-Deductible Debt Preservation
Section 66W Auction Pre-Approval Defenses
Renee Whitfield - Property Finance Contributor

“Borrowing money in Sydney is easy; structuring debt correctly to protect your tax deductions, avoid loan contamination under ATO rulings, and withstand bank valuation shortfalls is where wealth is protected. Never enter an auction room assuming pre-approval guarantees settlement.”

Renee Whitfield
Property Finance Contributor • Evylland Advisory Desk
Methodology

The 4-Step Capital & Debt Structuring Framework

A rigorous sequence designed to safeguard borrowing equity and prevent loan contamination.

01

APRA Stress Calibration

Model household borrowing capacity at +300bps above the standard variable rate to ensure cashflow survival through monetary tightening cycles.

02

Offset Preservation

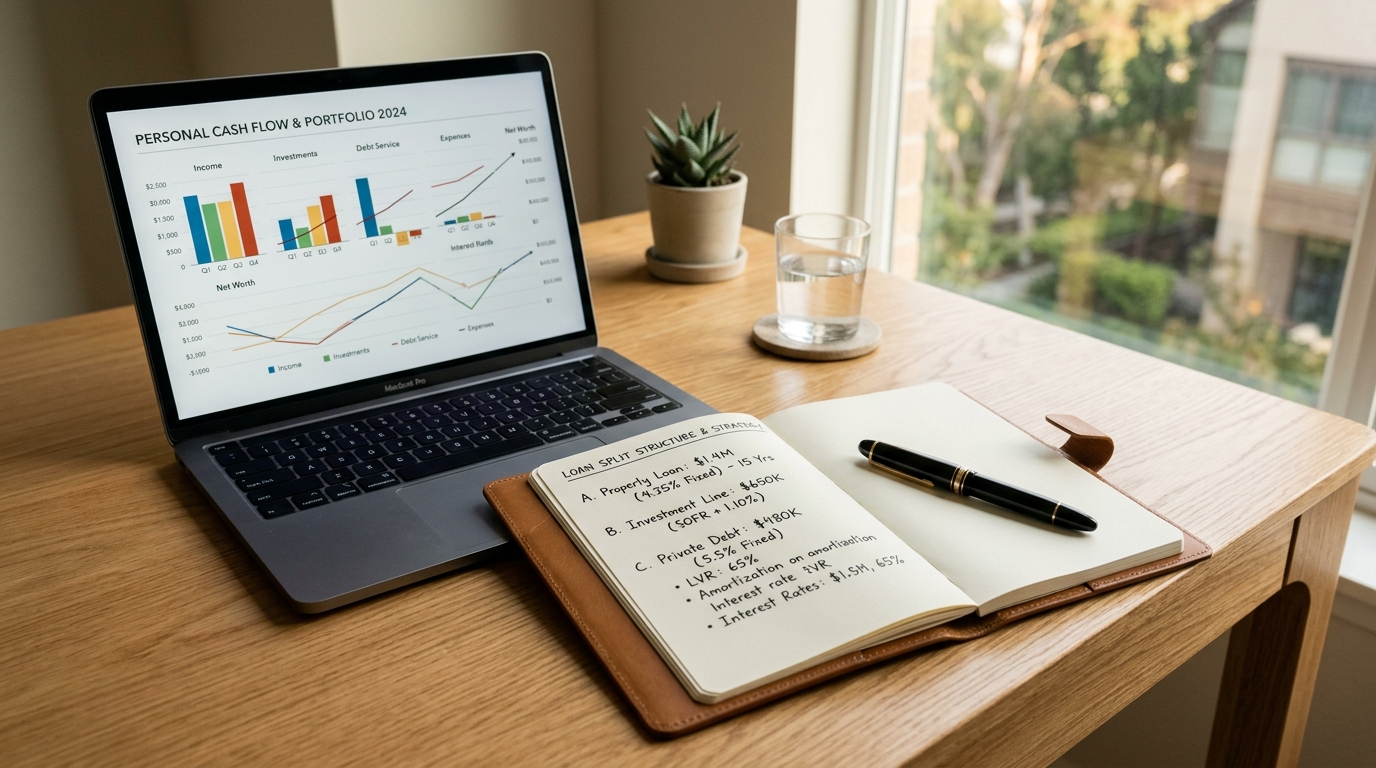
Route all spare liquidity exclusively through 100% offset sub-accounts, avoiding redraw drawdowns that compromise ATO deductibility.

03

Valuation Contingency

Establish a 5% to 10% secondary cash reserve before unconditional auction exchanges to absorb bank automated valuation model (AVM) shortfalls.

04

Uncross Loan Security

Insist on standalone mortgage securities across multiple lenders to prevent banks from controlling equity in your principal place of residence.

Strategic Advisory

Optimize Your Next Sydney Property Financing Structure

Need an independent assessment of your borrowing power, auction valuation risk, or debt structure? Our advisory team is ready to assist.

Request a Finance Advisory Brief

Direct Inquiries: [email protected]

General Advice Warning: The finance, credit, and debt structuring commentary presented in this Finance & Structuring Hub is provided strictly for general educational, analytical, and guidance purposes only and does not constitute personal credit advice under the National Consumer Credit Protection Act 2009 (Cth) or financial product advice under the Corporations Act 2001 (Cth). Borrowers must evaluate whether credit products suit their specific objectives, financial situation, and needs, and consult with an Australian Credit Licensee (ACL) or licensed mortgage broker prior to executing credit contracts.